
Nov’s picks for both SG Dividends and US Growth are live. Here’s how October performed.
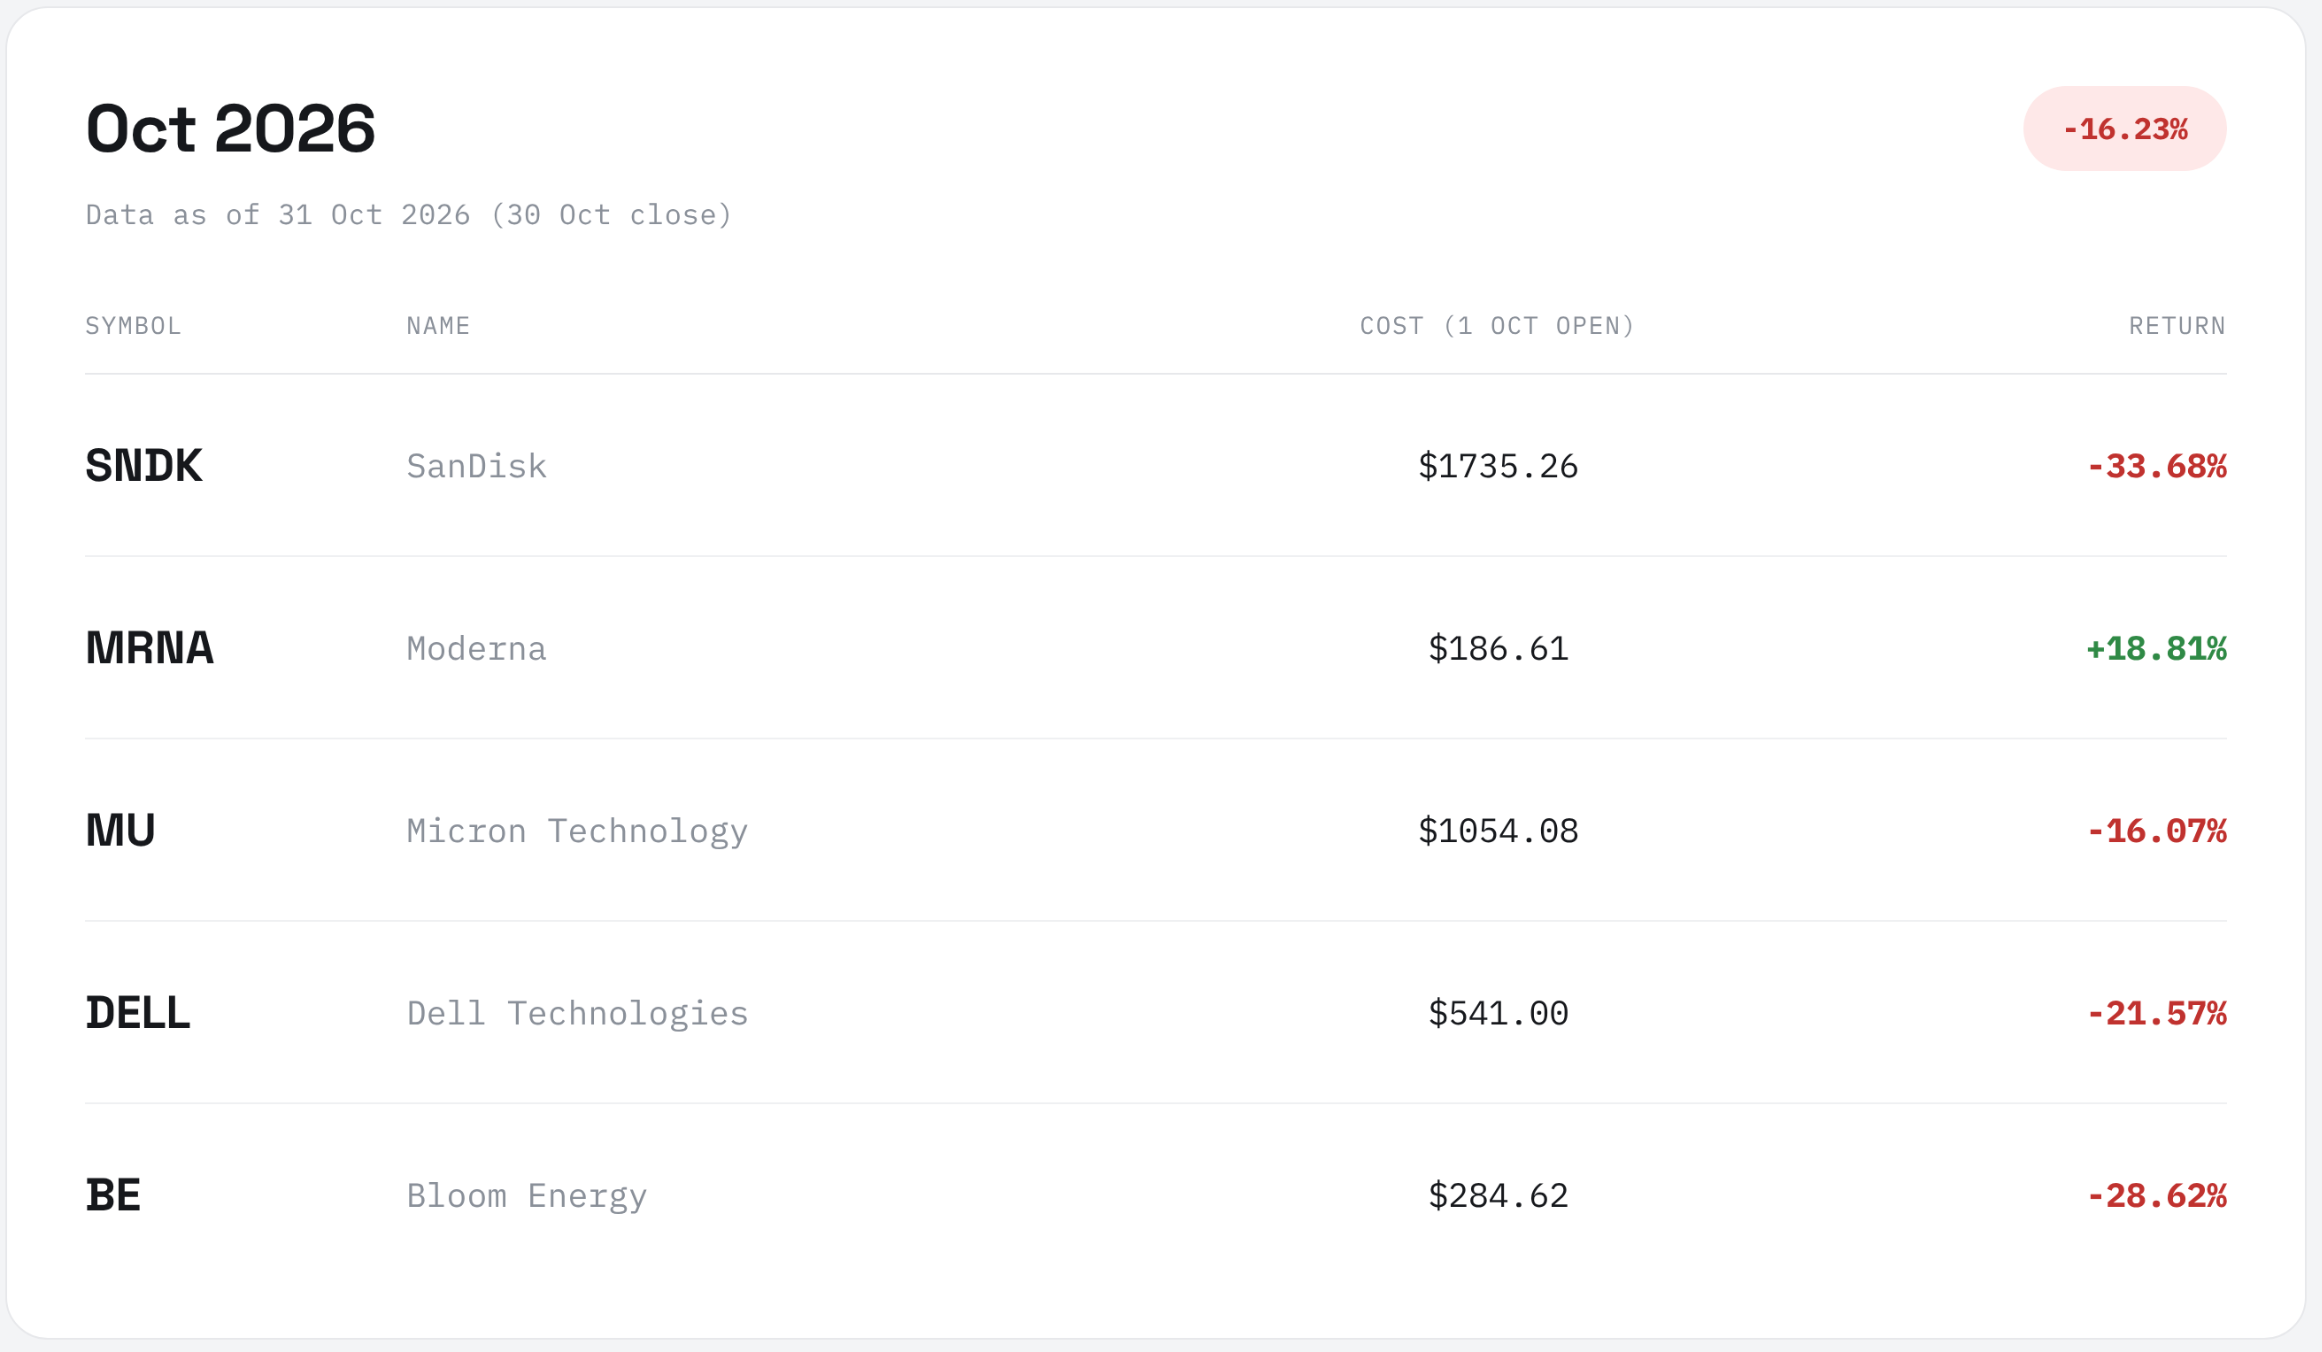
US Growth: -16.2%
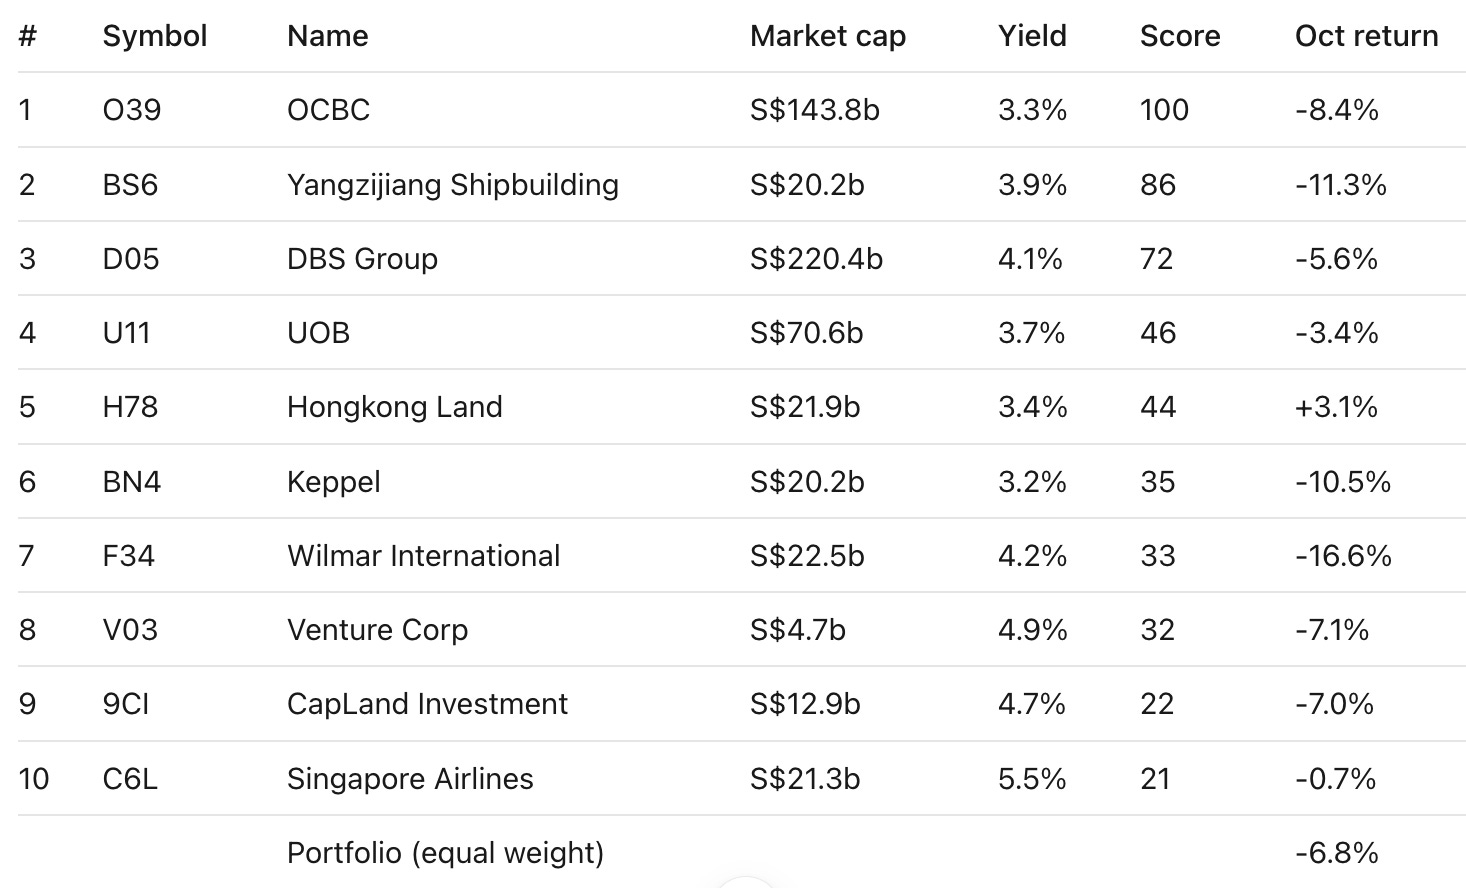
SG Dividends: -6.8%
October Review: A Red Month, and Why We Stay the Course
October was a red month for us. The SG Dividend portfolio closed 6.8% lower and US Growth slipped 16.2%. Not fun to look at, but not unexpected either after the run we’ve had this year.
Just a month ago the STI was at record highs. Then in the first full week of October, the index fell 4.1%, with OCBC, UOB and DBS leading the declines. The trigger was a mix of things. JPMorgan warned that surging long bond yields would hurt Q3 earnings for Southeast Asian lenders, and OCBC tumbled 5.9% in one session after Citi downgraded it to sell, wiping more than S$8 billion off its market cap. Some of this is plain profit taking.
Across the Pacific, US markets were choppier than the headline numbers suggest. The Nasdaq notched a record early in the month, but tech then cracked. On October 22 alone, the Nasdaq fell 2.6%, led by technology and communication services. Growth names felt that most, which is what dragged our US Growth portfolio.
So what do we do? Nothing dramatic. Our SG Dividend holdings still pay us to wait, with DBS offering a forward yield of 4.87% and UOB 4.59% based on early October estimates. The next real test is earnings, not price. DBS reports Q3 on 5 November and OCBC on 6 November, and that tells us far more about the businesses than one rough week of selling ever could. For US Growth, our rules decide entries and exits, not the headlines.
US Growth
SG Dividends
Disclaimer: This article constitutes the author’s personal views and is for entertainment and educational purposes only. It is not to be construed as financial advice in any form. Please do your own research and seek advice from a qualified financial advisor. From time to time, I have positions in all or some of the mentioned stocks when publishing this article. This is a disclosure - not a recommendation to buy or sell stocks.